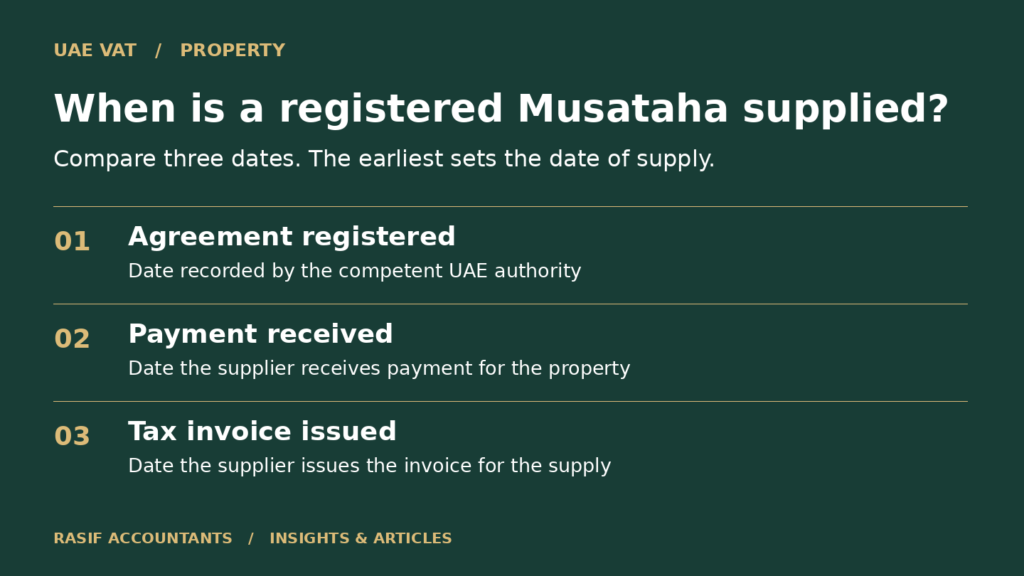
A landowner granting a property right under a registered Musataha agreement makes one indivisible supply of goods. The earliest of three events determines the date of supply. If the agreement is unregistered, the FTA treats the transaction as a supply of real estate under a lease.
Who should check the agreement?
Landowners granting development rights, businesses acquiring those rights and their finance teams should obtain evidence of registration with the competent UAE authority. A signed agreement alone does not establish the registration date.
Compare three dates before posting the transaction
- When did the competent authority register the agreement?
- When did the supplier receive payment for the property?
- When did the supplier issue the tax invoice for that supply?
For example, if the supplier receives payment on 2 December, registration follows on 5 December and the invoice is issued on 7 December, the date of supply is 2 December. Keep the payment evidence, registration confirmation and invoice together. If the agreement is unregistered, review the lease treatment separately. Check the property’s VAT classification before deciding what rate to apply.
Publication and effective date
The FTA issued Directive 7 of 2026 and listed it on 19 November 2026. The directive provides for publication in the Official Gazette and gives no separate commencement date. Read FTA Directive 7 of 2026 (PDF).
For help reviewing your records, explore Rasif’s VAT services or book a free 20-minute online consultation.