A taxable supplier can dispense with a tax invoice for a qualifying vending machine sale if it keeps sufficient evidence of the supply. VAT must still be accounted for. The rule affects suppliers selling goods or services through machines and operators collecting money for them.
Which machines qualify?
The customer must physically interact with an automated self-service device that delivers the goods or services immediately, without a person completing the supply on the supplier’s side. Staff may restock, service or monitor the device. A kiosk that sends an order to an employee for fulfilment does not qualify merely because it takes payment.
What should the supplier record?
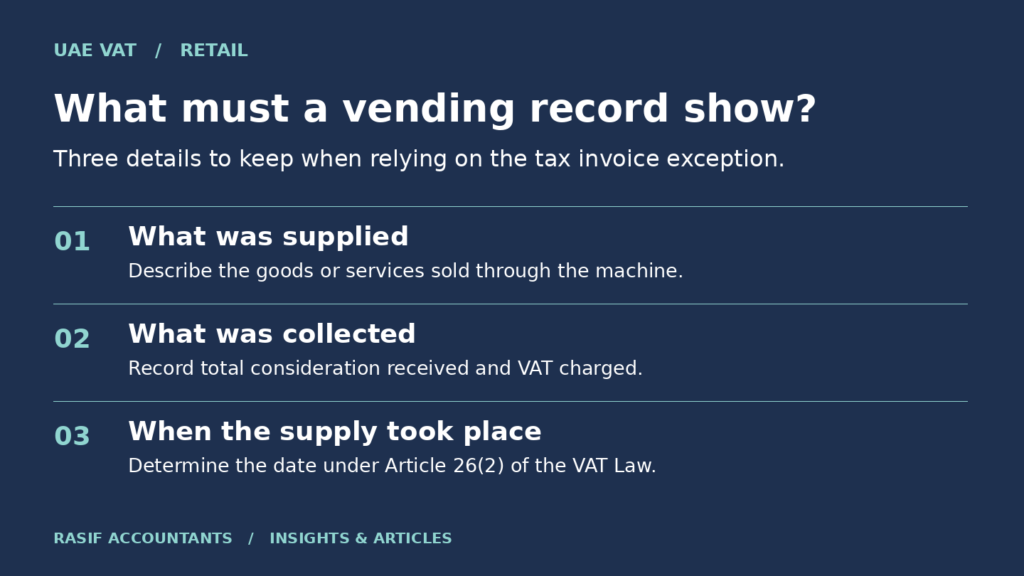
Keep the description of the goods or services, the total amount received and VAT charged, and the date of supply under Article 26(2) of the VAT Law. For a supplier operating its own machine, track when funds are collected. Reconcile collection logs with machine sales and the VAT ledger.
When another business operates the machine
Use the earlier of two dates: the date the supplier receives operator information confirming collection and specifying the amount, or the day after 30 days have elapsed since the operator collected the money. For example, if the operator collects on 1 December and the supplier receives a report confirming the amount on 4 December, use 4 December even if the bank transfer arrives later.
Ask the operator to report collection dates and amounts, record when each report arrives, and flag collections approaching the 30-day limit.
Publication and effective date
The FTA issued Directive 8 of 2026 and listed it on 19 November 2026. The directive provides for publication in the Official Gazette and gives no separate commencement date. Read FTA Directive 8 of 2026 (PDF).
For help reviewing your records, explore Rasif’s VAT services or book a free 20-minute online consultation.